

 Facebook
 X
 Pinterest
 Copy Link
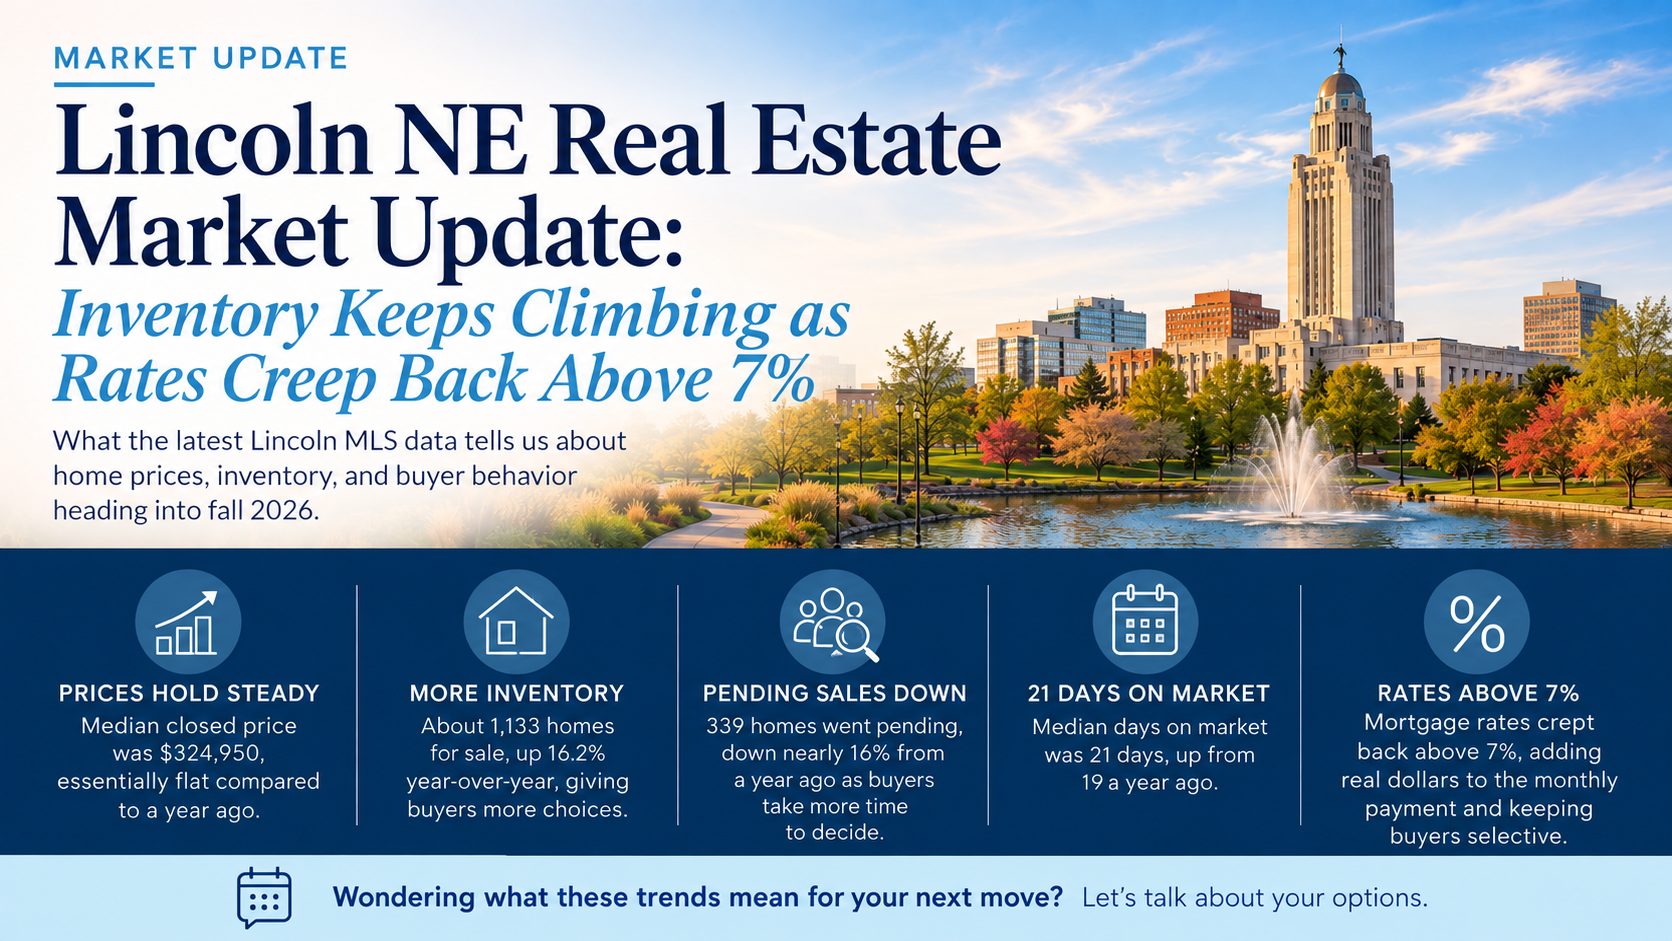
What the latest MLS data tells us about Lincoln home prices, inventory, and buyer behavior heading into fall 2026, and what today’s mortgage rate news means for anyone weighing a move.
There was a time, not very long ago, when a new Lincoln listing could set off a small scramble. Buyers wrote offers within hours, sometimes waived the things they’d normally ask for, because the fear of losing out felt bigger than the fear of missing something in the fine print.
Homes are still selling in Lincoln. But the mood keeps shifting, month by month.
August’s numbers show a market that’s steady on price but looser everywhere else, more homes to choose from, slower pending activity, and buyers taking real time to think before they act. And today, mortgage rates crept back above 7%, which only adds to the case for slowing down and doing the math before writing an offer.
That doesn’t mean Lincoln has flipped into a buyer’s market. It means we’re moving through a more selective one — the kind where preparation, pricing, and a clear-eyed view of the monthly payment matter for everyone at the table.
If you’re weighing where you fit into that shift, a good first stop is finding out what your Lincoln home is worth in today’s market.
A quick note on rates
As of today, mortgage rates ticked back above the 7% line, a threshold that had eased earlier this year but has crept back up over the past several weeks. Freddie Mac’s most recent weekly survey put the 30-year fixed rate at 7.03%, and daily trackers this week show it holding at or above that mark.
That matters how you read everything below. A rate near or above 7% adds real dollars to a monthly payment compared with where things sat even a few months ago – enough to change what a buyer can comfortably afford, and enough to explain some of what shows up in this month’s pending sales numbers.
What is happening in the Lincoln housing market right now?
The latest MLS data, current through August 2026, shows a market that’s still active but clearly rebalancing toward buyers.
Across the combined Lincoln market:
- Median closed price was $324,950, essentially flat compared to a year ago
- Median days on market was 21 days, up from 19 a year ago
- There were roughly 1,133 homes for sale, up 16.2% year-over-year
- Months of supply climbed to 2.9, up 16% from last year
- The median home sold for 99.0% of its final list price
- 339 sales went pending, down nearly 16% from a year ago
- 392 sales closed, down 9.9%
- 754 new listings hit the market, up 4.6%
Two things stand out here at once.
First, prices have essentially leveled off. After a long run of steady gains, August’s median closed price came in almost identical to a year earlier. That’s not a decline, but it’s a real change of pace from the double-digit growth we were seeing as recently as midsummer.
Second, and more telling: pending sales dropped nearly 16% even as new listings kept climbing. Buyers have more to choose from, and they’re taking longer to decide, which tracks with what’s happening to mortgage rates in real time.
Are Lincoln home prices still climbing?
Not the way they were a few months ago. August’s median closed price of $324,950 was essentially flat year-over-year, a sharp shift from the double-digit gains we saw earlier this summer.
One month never tells the whole story. Medians shift with the mix of homes selling, and a flat number doesn’t mean values are falling. But it’s worth sitting with this is the clearest sign yet that Lincoln’s long run of rapid price growth is settling into something closer to stable.
Existing homes actually posted a solid gain — median price up 3.1% year-over-year in August, while new construction pricing dipped slightly, down 0.3%. That split is worth keeping in mind if you’re weighing a resale against a new build this fall.
Is Lincoln a buyer’s market or a seller’s market?
Lincoln still leans toward sellers, but the margin keeps narrowing.
At 2.9 months of supply, we remain below what’s considered a balanced market — but that number is up 16% from a year ago, and existing-home supply alone jumped over 21% to 2.3 months. New construction supply sits at a full 7.0 months, a much looser market for builders than what resale sellers are facing.
With rates back above 7%, buyers are doing more math before they commit and it shows. Pending sales fell across both new construction (down 21.7%) and existing homes (down 15.1%) in August. Buyers haven’t disappeared. They’re taking longer, and leaning harder on:
- Whether the price reflects today’s rate environment, not last spring’s
- What the real monthly payment looks like at a rate near 7%
- Which homes have already handled the expensive stuff — roof, HVAC, windows
- Whether waiting for a better rate is worth losing this particular house
Why does a rate near 7% change buyer behavior so much?
It’s not just the headline number, it’s what that number does to a monthly payment. On a $325,000 loan, the difference between the rates buyers were seeing earlier this year and 7% today adds real dollars to the monthly cost, before taxes and insurance even enter the picture.
That’s enough to push some buyers out of a price range entirely, and enough to make others pause and recalculate rather than write an offer the same week they see a listing. It’s a meaningful part of why pending sales softened even as more homes came onto the market this month. The appetite hasn’t left, but the math takes longer to pencil out.
Why are some Lincoln homes still selling fast?
Even with rates higher and buyers more careful, well-prepared homes are still moving. Existing homes averaged just 16 days on market in August, a slight improvement from a year ago, even as new construction days on market nearly doubled to 56.
The difference usually comes down to the same things it always has: a home priced for today’s environment, photographed well, and free of the deferred maintenance that makes a buyer start doing mental math on repair costs on top of a higher payment.
Move-in-ready homes have an even bigger edge right now than they did earlier this year. When every dollar of the monthly payment counts more, buyers are less willing to take on a project.
What causes a home to sit longer right now?
The gap between a seller’s expectations and a buyer’s sense of value has only widened as rates have climbed. The price that made sense in June may not clear the same bar in September, simply because the buyer’s monthly budget shrank without the price moving at all.
Homes tend to sit when:
- The price was set before rates crept back above 7%
- Deferred maintenance adds to what already feels like a stretch at today’s payment
- The listing is competing against newer, better-prepared homes in growing inventory
What this means if you’re selling
Pricing precision matters more now than it has in months. With inventory up over 16% and buyers doing more careful math against a rate near 7%. A home priced even slightly ahead of the market risks sitting through the fall rather than moving quickly.
The good news: homes that are priced right and show well are still closing near full list price, 99.0% on average in August. That tells you buyers haven’t left. They’re just more deliberate about which homes are worth acting on quickly.
This is also a good season to lean on rate buydowns or seller concessions as a negotiating tool rather than a straight price cut. A temporary or permanent buydown can make your home’s monthly cost competitive without moving the sale price at all — worth discussing before you list.
What does this mean if you’re buying
More inventory and softer competition give you room to be selective, but a rate near 7% means your pre-approval number matters more than ever. Get a clear, current number from your lender before you start touring. What you could afford a few months ago and what you can afford today may be two different homes.
Existing homes are still moving quickly when they’re priced and presented well, a median of 16 days, so don’t assume every listing will still be there in two weeks. You can start browsing current Lincoln homes for sale to get a feel for what’s out there.
But homes that have lingered, or that need some work, may leave real room to negotiate, either on price or through a rate buydown built into the deal. If today’s rate has you wondering whether to wait, it’s worth running the numbers on both paths: buying now with a plan to refinance later if rates ease, versus waiting and hoping for a better rate on a market where inventory, and your options, could tighten again once conditions shift.
The takeaway for Lincoln buyers and sellers
Lincoln’s market hasn’t flipped, it’s recalibrating. Prices have leveled off after a long stretch of gains, inventory keeps growing, and mortgage rates creeping back above 7% are giving buyers real reason to slow down and do the math before they commit.
Homes that are priced for today’s conditions and show well are still selling close to full price, often quickly. Homes priced for last spring’s market are the ones sitting.
For sellers, that means precision matters more than optimism. For buyers, it means more selection and more negotiating room, if your financing is ready to move when the right home shows up.
If you’re wondering how your home, your neighborhood, or your price range fits into today’s market, let’s talk it through. No pressure – just a plan.
Source: Great Plains Regional MLS InfoSparks reports for the Lincoln Area Region, current as of September 13, 2026, reflecting August 2026 activity. Mortgage rate data from Freddie Mac’s Primary Mortgage Market Survey and daily rate trackers as of September 28, 2026. Market conditions vary by neighborhood, price range, property type, and condition.
Kathy Ley, REALTOR®, GRI, CLHMS Coldwell Banker NHS Real Estate | Coldwell Banker Global Luxury Your Style • Your Story • Your Home #KathyLeyRealtor #LincolnHomesForSale #ColdwellBankerNHSRealEstate


